Stratifi
A safety-first workspace for systematic trading research.
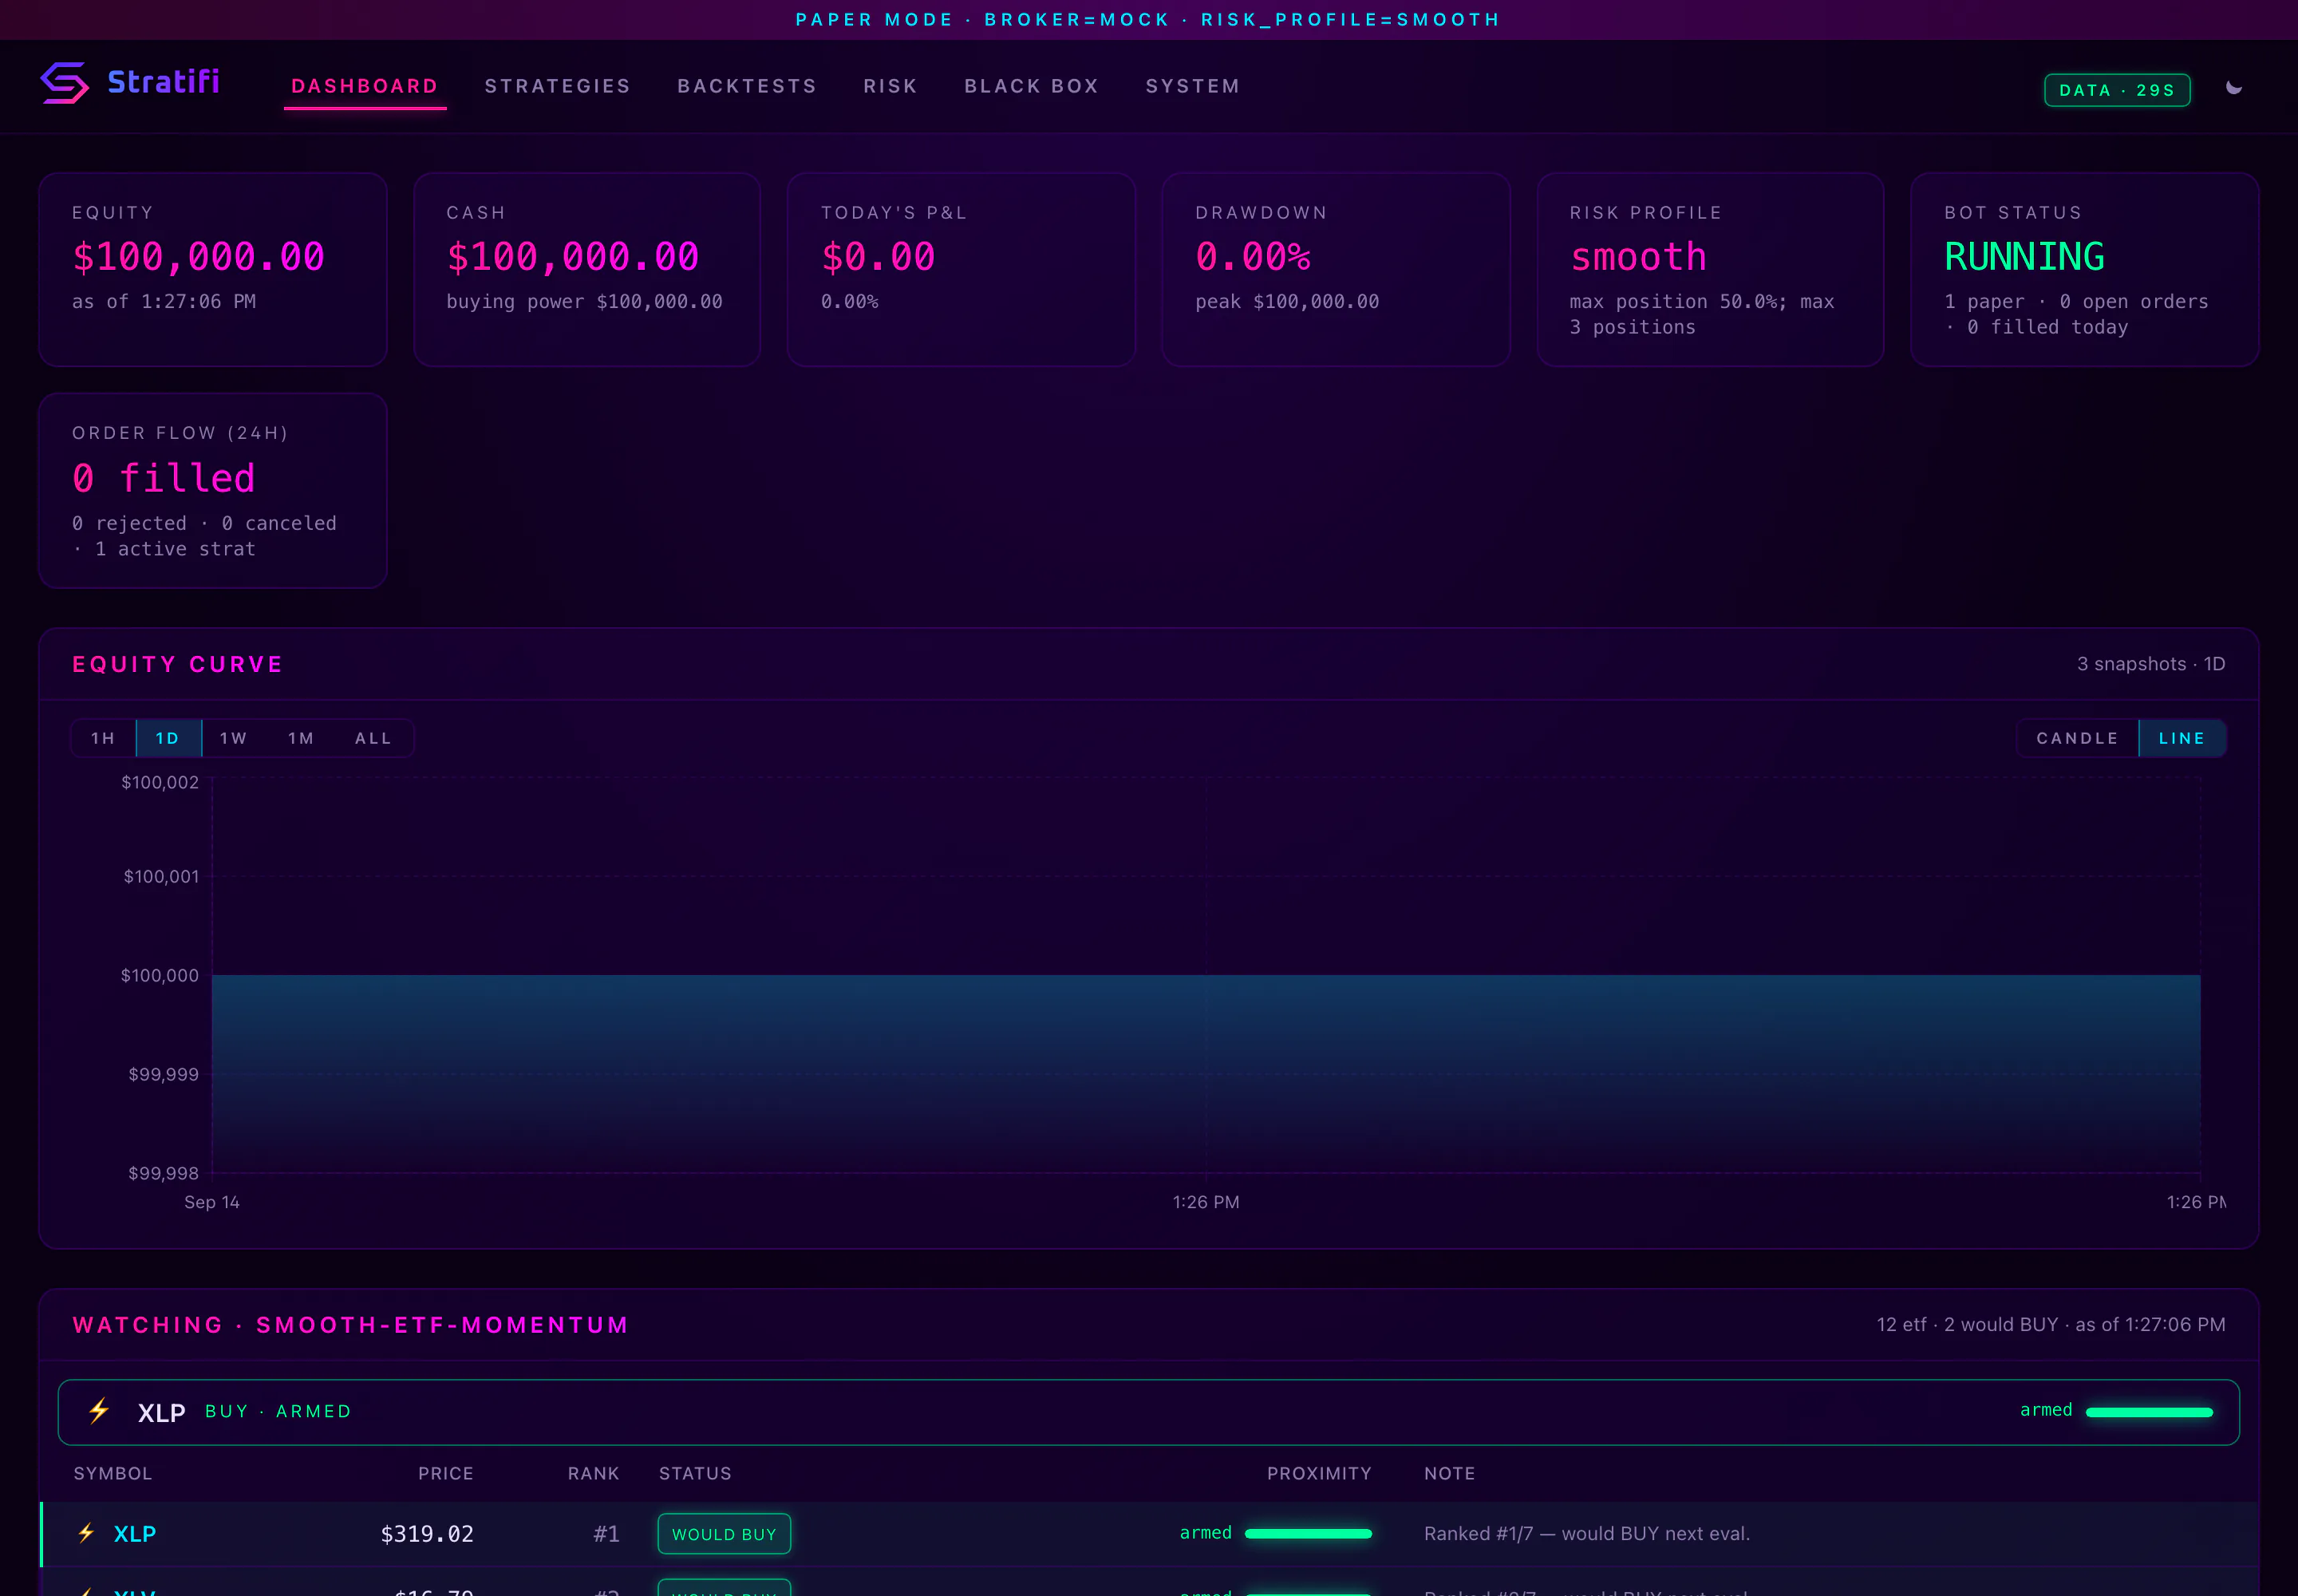
A personal trading platform that brings strategy research, paper execution, risk controls, audit trails, and validation evidence into one disciplined workspace.
- Status
- PRIVATE RESEARCH BUILD
- Source
- Private
- Capabilities
The problem
Systematic trading research is only useful if its evidence can be trusted. A backtest that draws a clean-looking equity curve from flawed assumptions is more dangerous than an obvious failure.
Stratifi brings strategy research, paper execution, and risk controls into one workspace built around that concern.
The system
Strategy library
Strategies are pure functions with no I/O, so the same logic drives backtests and paper trading.
Backtesting
Fills at the next bar’s open with modelled slippage and commission. Daily-bar backtests are treated as reliable; intraday ones are not.
Validation
Cost-stress reruns and walk-forward tests decide whether a result is fit to act on.
Risk engine
Every order passes checks for loss, drawdown, exposure, sizing, data freshness, and trading hours, and every result is recorded.
Paper execution and kill switches
Orders go to a paper-trading broker adapter or a deterministic mock, with system lock, pause, and manual close controls.
How it was built
A React and TypeScript interface built with Vite talks to a Python FastAPI service. PostgreSQL stores strategies, backtests, orders, risk checks, and audit events, and scheduled jobs drive the strategy loop.
Orders flow from a strategy through the risk engine to an execution service and a broker adapter. The only broker integration is Alpaca paper trading, and live trading is disabled by default.
Research
- Strategy library
- Backtest engine
- Validation
Decide
- Strategy service
- Risk engine
Execute
- Execution service
- Alpaca paper adapter
- Mock broker
Record
- PostgreSQL
- Risk checks and audit events
Technology
Design decisions
The risk engine never short-circuits
Every check runs on every order and each result is stored, so a blocked trade always shows all of its reasons.
One sizing formula
Backtests and paper trading size positions the same way, so research and execution stay comparable.
Validation is part of the engine
Robustness checks run as part of analysis rather than as an optional habit. An edge that disappears under higher costs is not treated as an edge.
Decimal money math
All monetary calculations use decimal arithmetic rather than floating point.
Selected views
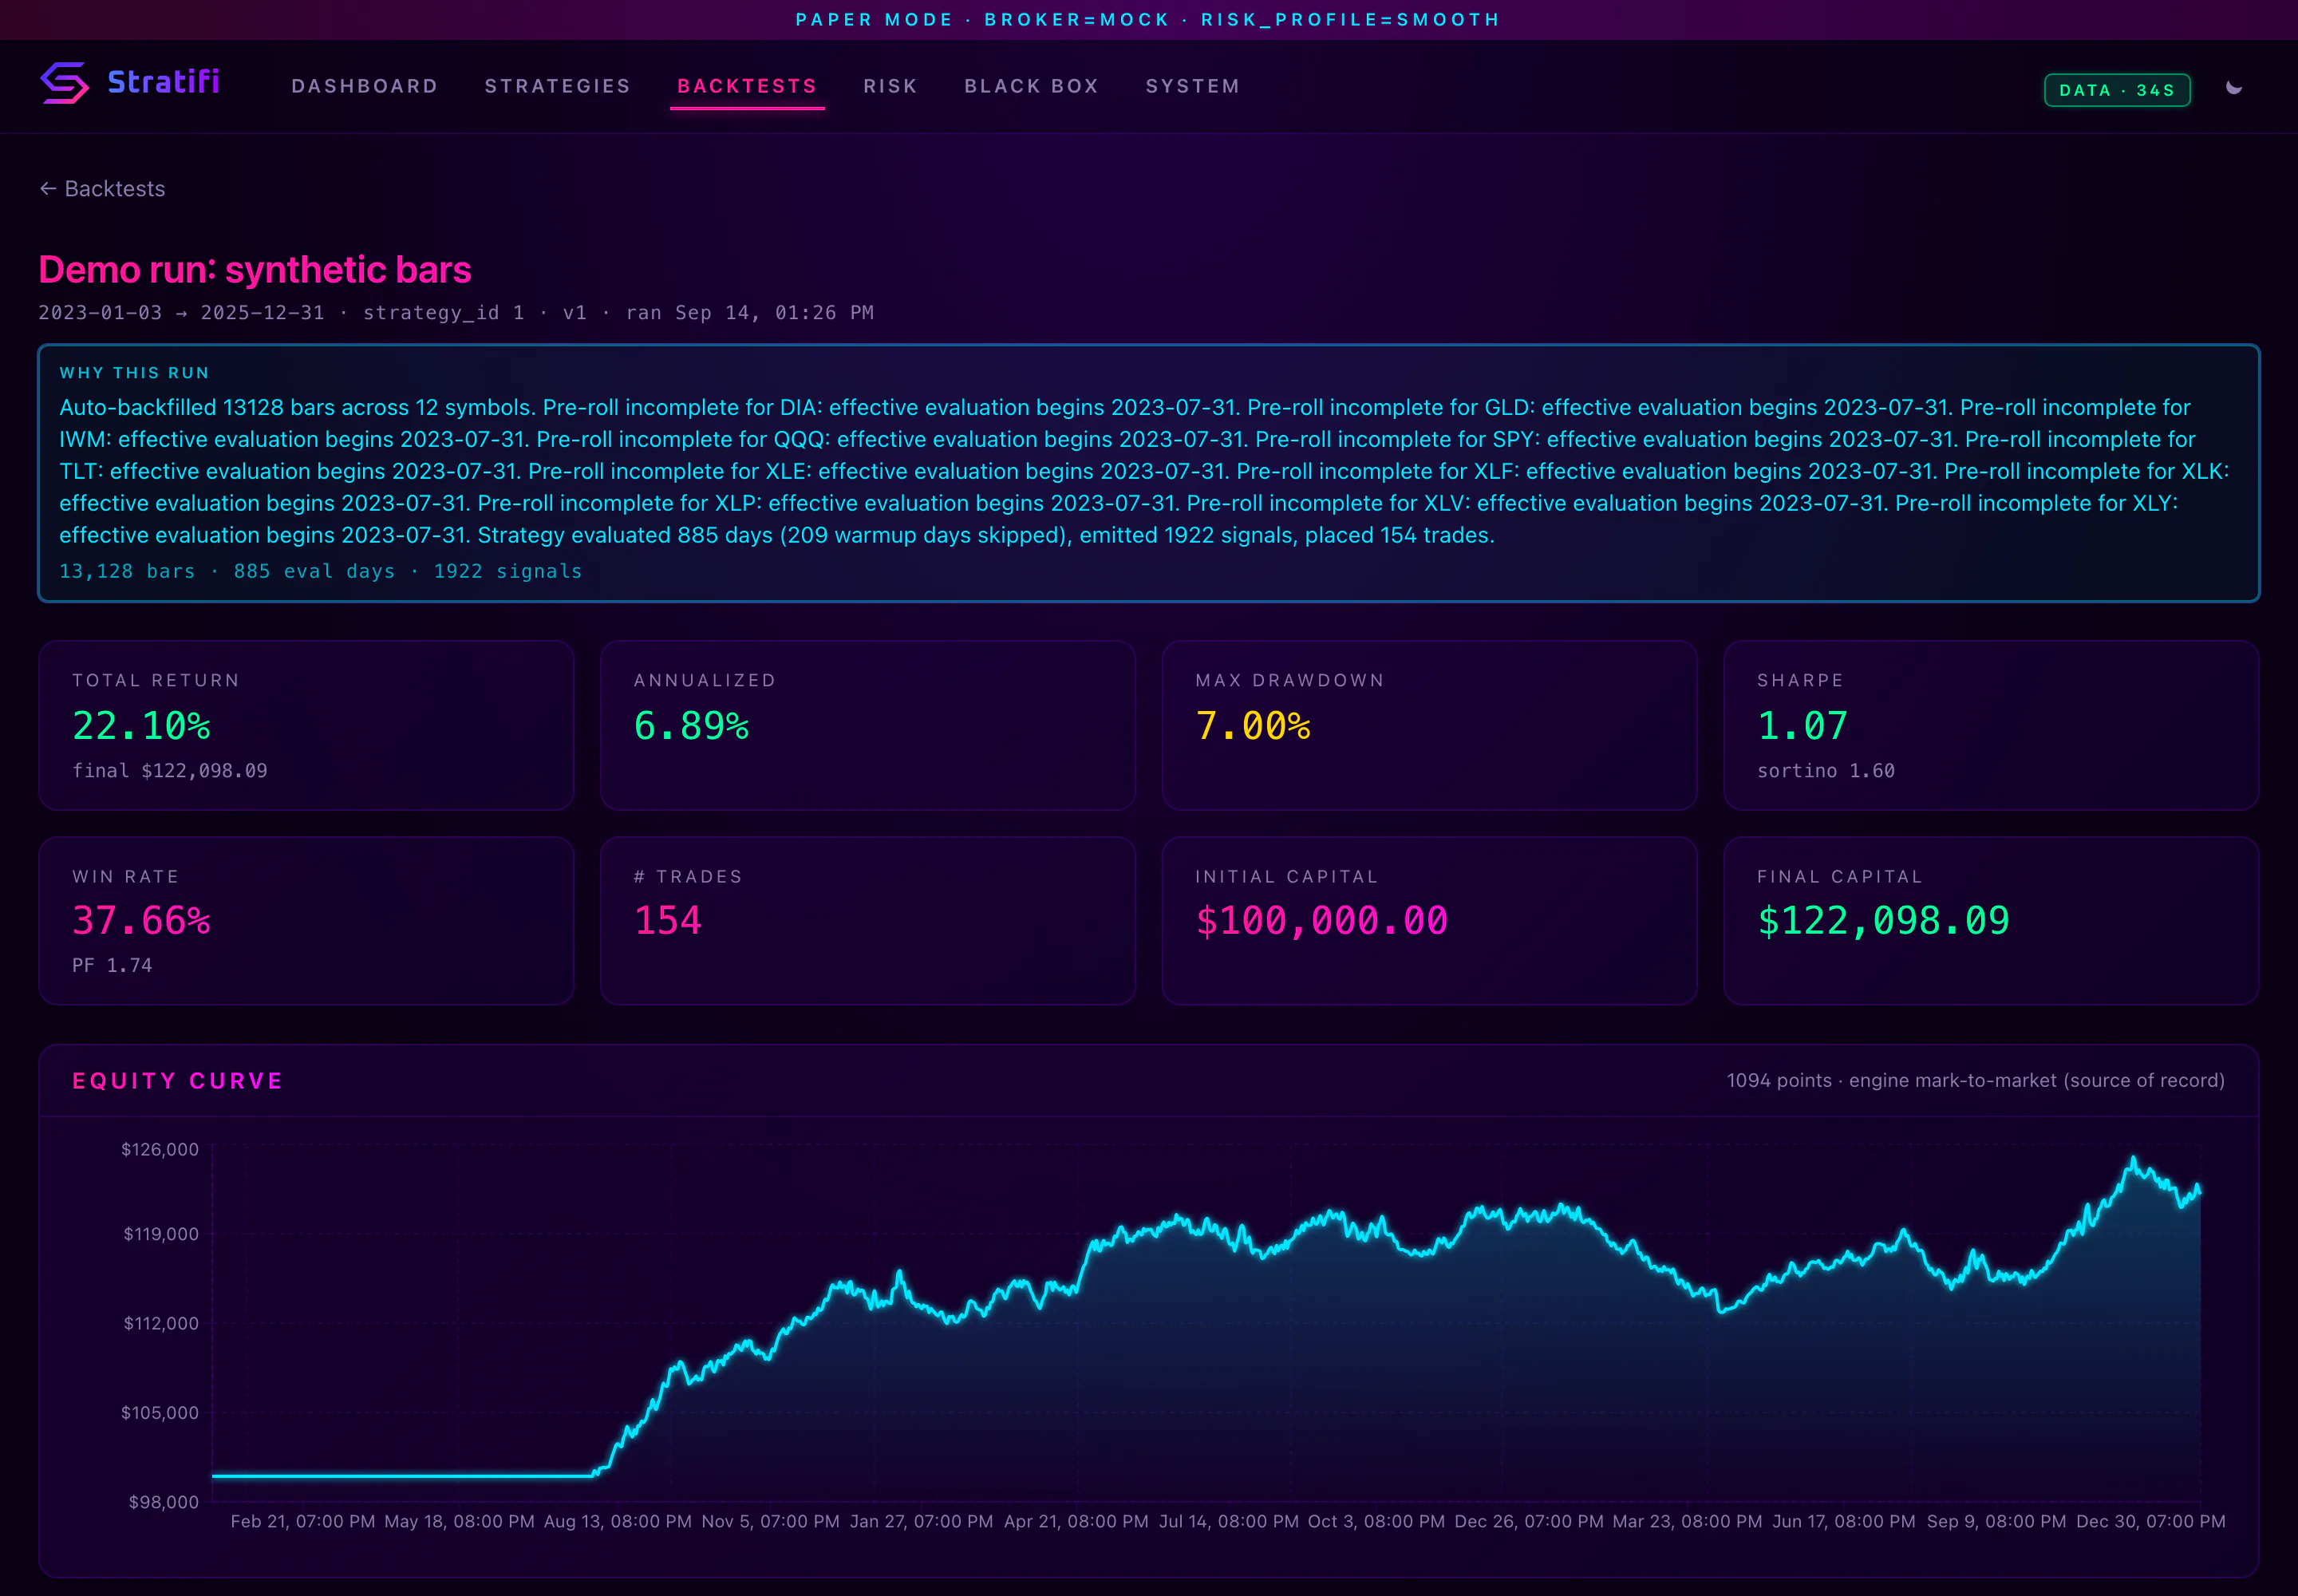
Synthetic dataBacktest detailAnalysis and validation evidence for a demo backtest on synthetic price history. The results are not real performance. 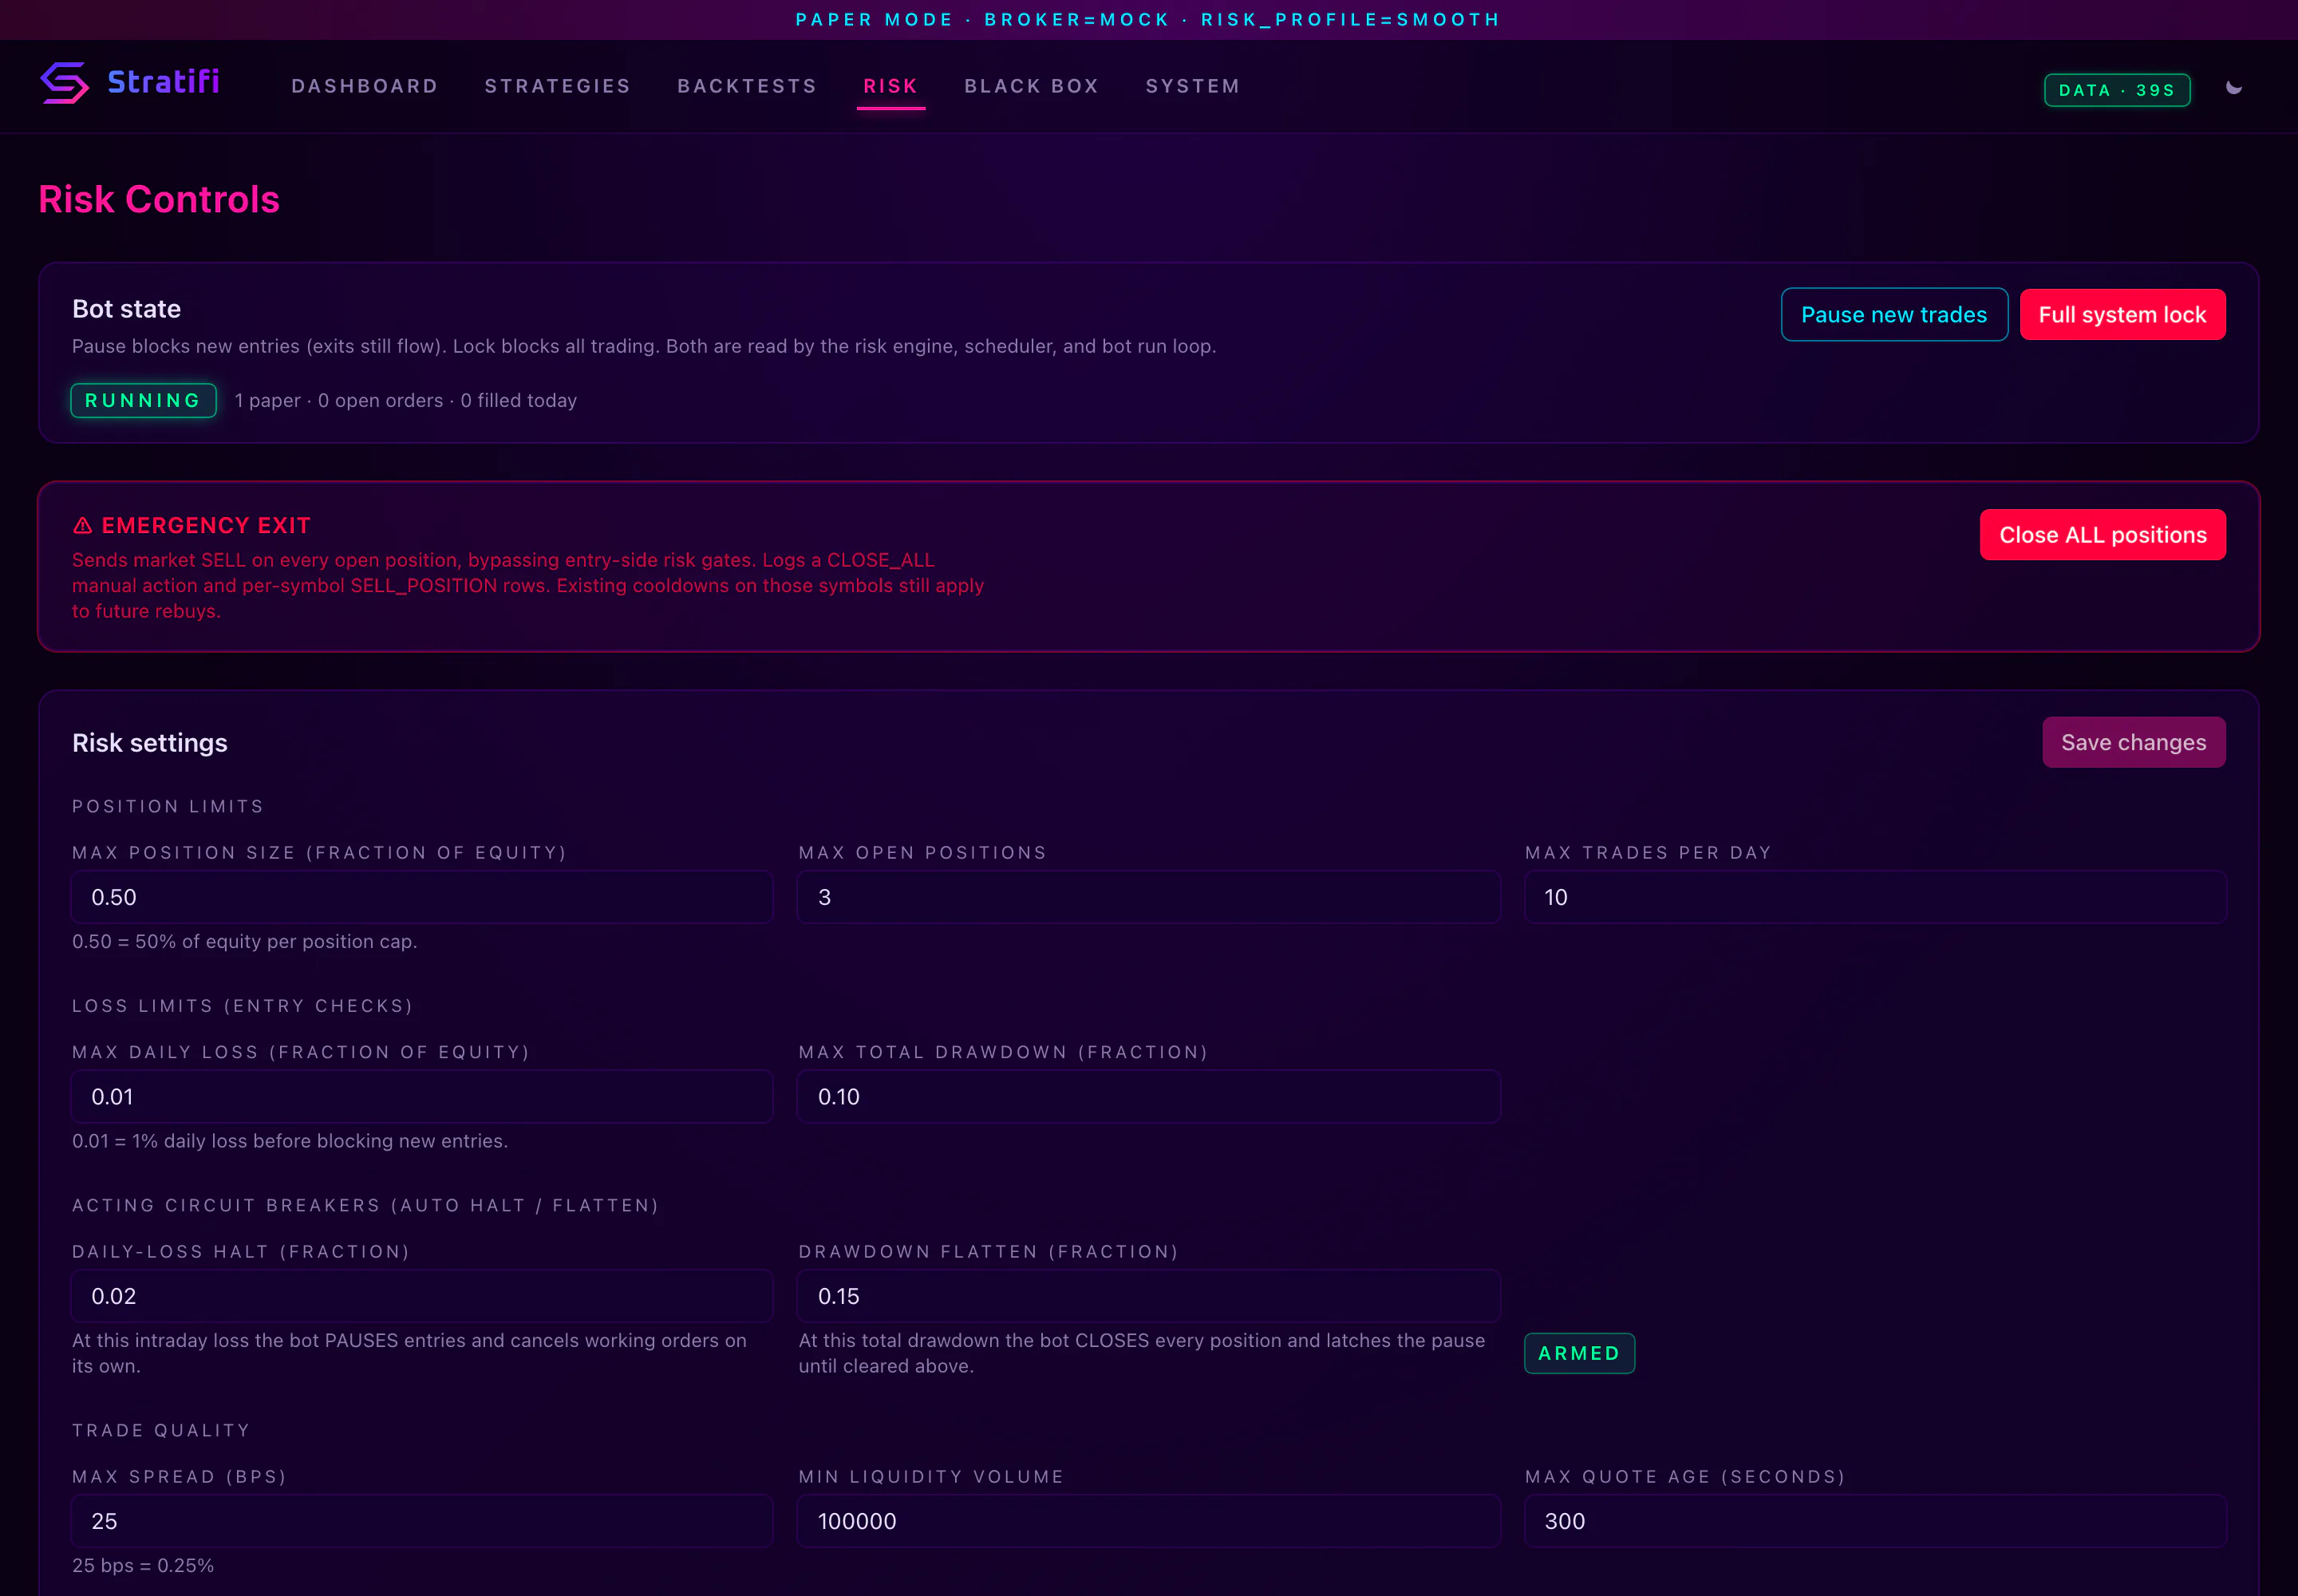
Demo dataRisk and systemRisk controls, bot state, and the emergency exit, with demo values and no account details. 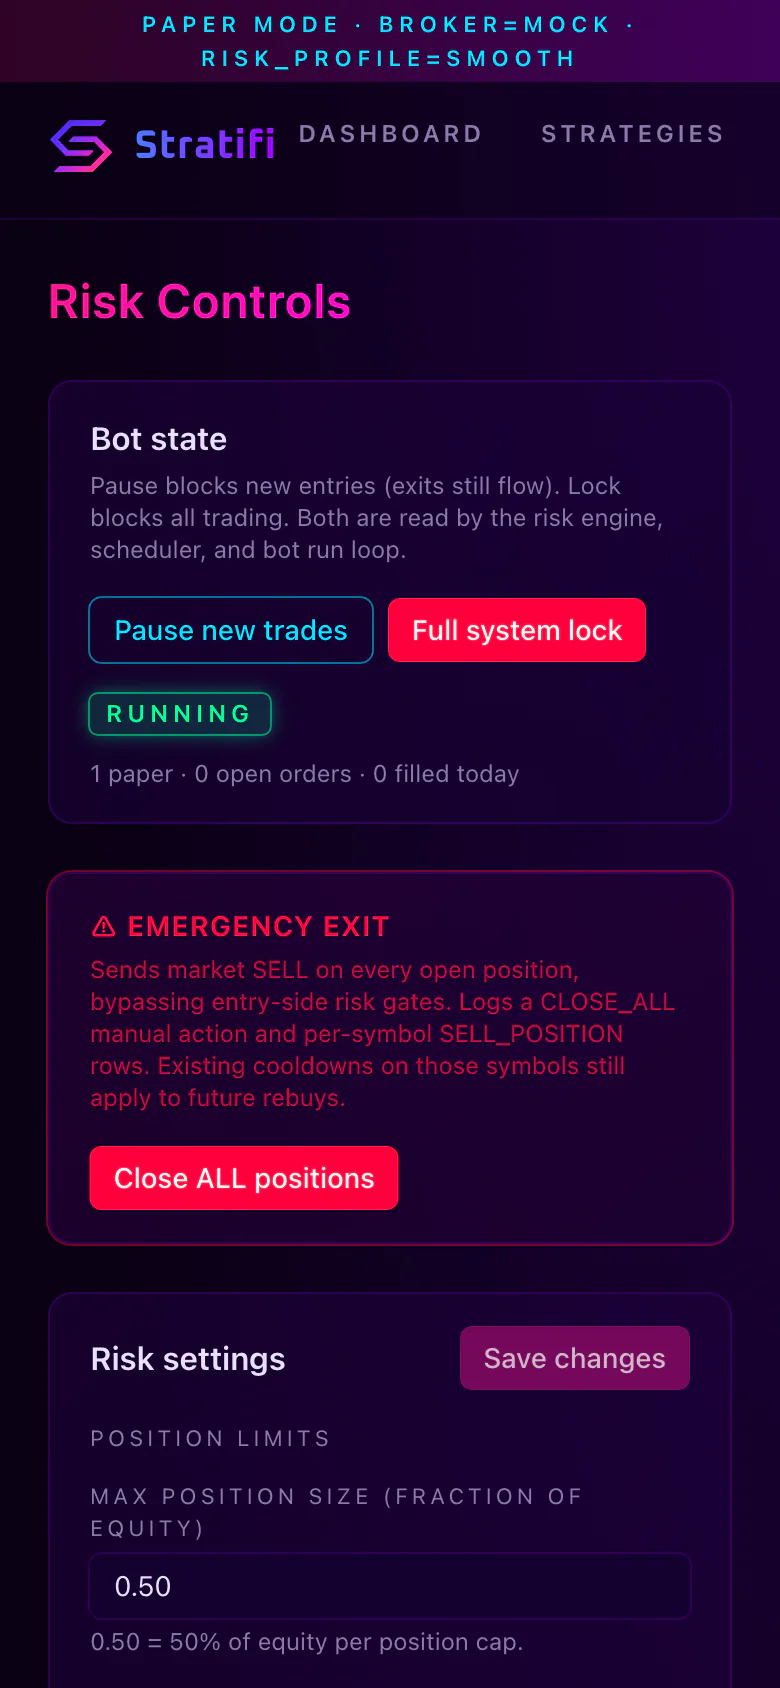
Paper tradingOn a phoneRisk controls at a 390px viewport, with the paper mode banner in view.
Current state
Private research build under active development. It runs against paper trading only, intraday backtests are not treated as reliable, and market-regime rotation is still untested. The source code is private.